Key Takeaways
- Founders with 5–75M in business value are often the most expensive person on their advisory team because they spend irreplaceable time coordinating advisors who do not coordinate with each other.
- Traditional advisor structures are built around lanes, not outcomes, and the gaps between those lanes are where tax exposure, governance failures, and exit regret accumulate.
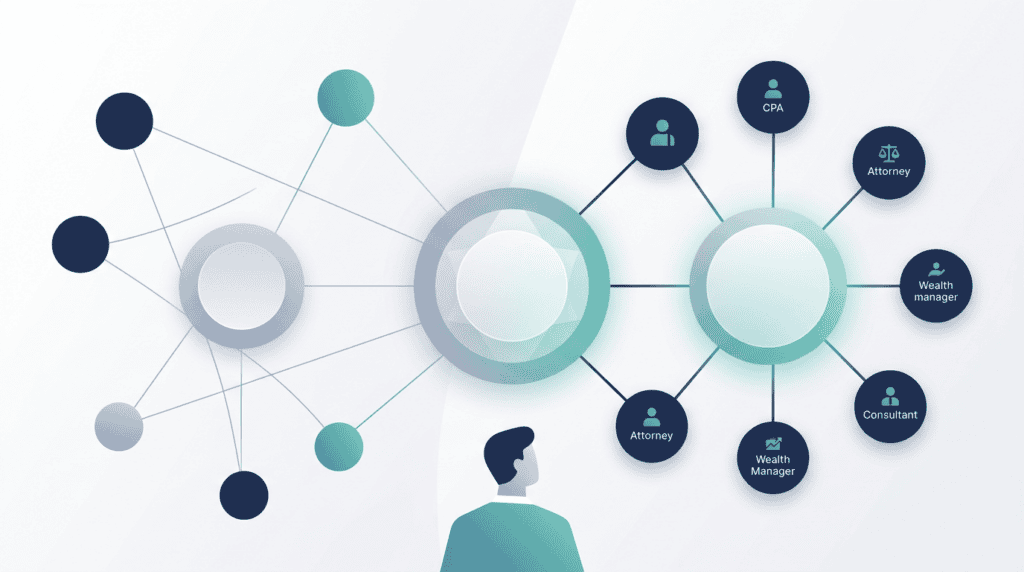
- A fractional family office is not a replacement for existing advisors; it is a planning hub that sits above and between them, turning separate conversations into one coordinated system.
- The Founders Freedom System, built around Freedom Point modeling and lifetime cash flow visibility, provides the backbone for integrated, proactive planning.
- Most founders discover they have a coordination problem only when a deal falls through, a tax event blindsides them, or an exit brings to light that their wealth plan never truly accounted for the business.
Article at a Glance
Many 5–75M founders believe they have a strong advisory bench because they have a CPA, an attorney, a wealth manager, and sometimes a consultant they trust. The reality is that these relationships typically operate in parallel, not as a unified planning system. The founder becomes the default integrator, translating between advisors, reconciling conflicting recommendations, and carrying planning risk that no one else owns.
This article examines why that lane based model breaks down at the 5–75M level, what a fractional family office changes structurally, and how to diagnose whether the problem in your world is individual advisors or the absence of a planning hub. It then walks through practical steps for transitioning into a fractional family office without disrupting trusted relationships, using composite founder scenarios to show how the model works in practice.
ClearPoint is not a tax, legal, or business advisory firm. It coordinates your existing professional team and integrates their inputs into a unified planning system so you can move forward with clarity and confidence.
Why Traditional Advisor Models Break Down At The 5–75M Level
Each Advisor Optimizes For Their Own Lane
Most founders at this level have built relationships over years:
- A CPA focused on minimizing this year’s tax bill.
- An estate attorney who drafted trusts and operating agreements.
- A wealth manager overseeing investable assets.
- Perhaps a business consultant focused on growth or operations.
Each advisor brings real value, but each is accountable only for a slice of the system. The CPA optimizes tax outcomes in isolation. The estate attorney designs structures without full visibility into business dynamics. The wealth manager manages a portfolio that may not incorporate the business’s risk profile or eventual exit. When every specialist optimizes locally, the global picture can drift in directions no one intended.
This is not a failure of any individual professional. It is a structural limitation of lane based advice. No one is hired to own the full system: business value, personal freedom, tax, estate, and legacy across time.
The Coordination Tax Founders Pay
The coordination gap shows up as a hidden, compounding tax on the founder:
- Time: Hours spent briefing each advisor separately, repeating context, reconciling conflicting recommendations, and serving as the relay between professionals who rarely meet together.
- Decision drag: Key decisions such as refinancing, restructuring, compensation changes, charitable commitments, or a potential sale stall because no one can see enough of the picture to give confident guidance.
- Tax leakage: Without a unified, multi year tax strategy that connects the business, personal income, and estate goals, founders pay more than necessary, not from any single error but from plans that were never designed to fit together.
- Exit regret risk: When a liquidity event approaches, the founder discovers that the wealth plan, estate structures, and business valuation assumptions were never aligned around a shared exit timeline and post exit life.
None of these costs appears on an engagement letter. They accumulate quietly until a transaction, lawsuit, tax event, or family transition forces them into the open.
Loyalty To Legacy Advisors And Structural Blind Spots
Founder loyalty to long time advisors is understandable and often deserved. Those relationships have helped navigate early growth, stress, and survival. The problem is not the advisors themselves; it is the pattern that loyalty can obscure.
The key question is not whether your CPA is competent or your attorney is thoughtful. It is whether your CPA, attorney, wealth manager, and other specialists operate from a shared plan, with shared assumptions, toward shared outcomes. For most founders in the 5–75M band, the honest answer is no.
The result is a system in which individual advisors are doing good work in their lanes while the total picture remains fragmented. At this scale, fragmentation itself becomes a risk factor.
What A Well Coordinated Fractional Family Office Looks Like
One Hub With Every Advisor In Their Lane
A fractional family office does not try to become your CPA, attorney, or wealth manager. It sits above and between them as a planning hub that owns coordination and system level thinking.
The model looks like this:
- The CPA continues to handle tax compliance and technical planning.
- The estate attorney continues to design and maintain legal structures.
- The wealth manager continues to oversee investments.
- Insurance and risk specialists continue to do their work.
The difference is a central hub that:
- Maintains one integrated planning model covering business value, personal balance sheet, tax exposure, and legacy structures.
- Clarifies scopes so each advisor knows their role in the broader plan.
- Surfaces conflicts between strategies before they show up as problems.
- Routes multi domain decisions through a single lens so tax, legal, business, and estate implications are considered together.
In practical terms, this is the difference between the founder serving as the translator and a dedicated planning team coordinating the conversation.
Business And Personal Wealth Planned As One System
For a 5–75M founder, the operating business is usually the dominant asset. It drives income, concentrates risk, and determines when personal financial freedom is possible. Yet most traditional planning treats the business and personal wealth as separate universes.
A functioning fractional family office closes that gap through coordinated workstreams:
- Freedom Point modeling that defines the level of personal liquidity and passive income at which work becomes optional, then links business, compensation, and exit decisions back to that target.
- Lifetime cash flow visibility that incorporates business distributions, personal spending, tax obligations, and estate transfers into an integrated scenario set rather than a single projection.
- Ongoing enterprise value planning that evaluates where value is today, what threatens it, and what specific initiatives can improve attractiveness and transferability in line with likely transition windows.
- Estate and legacy planning that is built around real liquidity timing and entity structures instead of generic documents that assume static values.
These elements are not add ons to traditional advice; they depend on cross domain coordination. Without a hub, each piece remains partial.
The Freedom Point As A Coordination Anchor
Freedom Point is a specific, calculated threshold, not a vague sense of “enough.” It reflects:
- Required lifestyle spending and commitments.
- Business distributions and potential sale proceeds.
- Tax drag under different deal and planning structures.
- Estate goals and multi generational transfers.
- Investment risk and return assumptions over time.
When this number is documented and stress tested, every major decision looks different. Capital investment, owner compensation, distributions, exit timing, philanthropy, and family support can be evaluated against a clear picture of what true freedom requires. The work to build that picture is inherently integrative, which is why it fits naturally inside a fractional family office rather than a siloed advisor model.
The Advisor Coordination Audit
Before restructuring anything, founders benefit from a sober look at how their current system actually works. The Advisor Coordination Audit is a practical framework to assess coordination, not competence.
1. Map Every Advisor And Identify System Ownership
List every professional with a meaningful role:
- CPA or accounting firm.
- Estate and business attorneys.
- Wealth manager and investment advisors.
- Business consultants or brokers.
- Insurance and risk specialists.
- Bankers and lenders.
For each, note:
- Mandate and primary focus.
- Last instance of proactive outreach that was not prompted by you.
- Visibility into what other advisors are doing.
- Participation in any shared planning sessions.
Then ask one question: who is accountable for how all of this fits together? If the answer is “me,” you have identified the first coordination gap. The role is important, but it is costly for the founder to hold personally.
2. Review Coordination Across The Business Value Lifecycle
Look at the lifecycle of your business value from today through eventual transition:
- How is current value assessed, and who participates in that conversation?
- What is in place to protect value across tax, legal, risk, and operational dimensions?
- Which initiatives are explicitly aimed at making the business more attractive and transferable?
- How clearly have you defined what a successful transition looks like for you personally and for the enterprise?
If these phases exist only as ad hoc discussions within individual relationships, the system does not yet have an integrated enterprise value plan.
3. Identify Gaps Between Business Value And Personal Wealth Planning
Review your most recent personal financial plan. Look for concrete references to:
- Current estimated business value.
- Potential sale structures and timing.
- After tax proceeds under different scenarios.
- The role of business income and eventual liquidity in retirement or Freedom Point planning.
If the operating business appears only as a generic asset or not at all, there is a disconnect between how value is being built and how personal freedom is being modeled. That disconnect touches tax, estate structures, insurance, and investment decisions simultaneously.
4. Test Alignment Between Legacy And Exit Goals
Ask two questions:
- Do estate structures reflect current entity ownership, values, and likely liquidity events?
- Does the contemplated exit timeline reflect both market realities and personal Freedom Point readiness?
If estate planning and exit planning have occurred in separate conversations, using different assumptions, the family is relying on documents and strategies that may no longer match the real situation. The risk is not theoretical; it shows up in tax exposure, family conflict, and missed opportunities when transitions occur.
5. Decide What To Keep, Coordinate, Or Replace
The output of the audit is not a list of advisors to dismiss. In many cases, existing relationships remain the right ones. What changes is:
- Introduction of a planning hub with system level accountability.
- A new communication cadence that brings key advisors together periodically.
- Clear scopes that distinguish technical responsibility from coordination responsibility.
Advisors who are strong in their lanes and receptive to integrated planning are kept and elevated. Gaps where capacity, specialization, or fit are inadequate are addressed deliberately.
How The Transition Works In Practice
Scenario One: Five Good Advisors And No Unified Plan
A founder in her mid fifties ran a manufacturing company that had grown from startup to eight figure value. Over two decades she assembled:
- A CPA firm that knew the business from inception.
- An estate attorney who updated documents twice over the years.
- A regional wealth manager overseeing personal investments.
- A business broker she occasionally consulted.
- An insurance advisor who had placed several policies.
No one had ever shared a room or call together.
When she engaged a fractional family office and ran the coordination audit, the first discovery was that her estate plan assumed a business value from three years prior, before a major growth phase. The discrepancy created unnecessary exposure under several plausible exit scenarios. The transition process:
- Convened existing advisors to align on current valuations and goals.
- Updated estate structures to reflect realistic business value and possible timelines.
- Linked investment strategy and personal Freedom Point modeling back to the business’s trajectory.
No advisor was replaced. The change came from installing a hub to manage the system rather than leaving coordination in the founder’s hands.
Scenario Two: Pre Exit Offer Without A Unified Model
A technology services founder in his early sixties received an unsolicited acquisition offer at a seemingly attractive multiple. His advisors responded from their lanes:
- The CPA modeled tax implications of the proposed structure.
- The wealth manager projected portfolio outcomes based on net proceeds.
- The estate attorney raised concerns about current structures at that scale.
None of them could answer the central question: what does this deal mean for life, freedom, and family, under realistic scenarios?
After engaging a fractional family office, the first three months focused on:
- Building an integrated model connecting business valuation, after tax proceeds, Freedom Point requirements, and estate implications.
- Comparing alternative deal structures and timings against that model.
- Providing a single, coordinated view that advisors could use to refine their own technical work.
The founder eventually negotiated a modified transaction aligned with the integrated plan. The fractional family office did not supplant the existing advisors; it gave them a shared framework.
Scenario Three: Multi Entity Complexity Without Consolidated Planning
A founder held interests in two operating companies, several real estate entities, and a family partnership. Accounting, banking, and advisory relationships were scattered. Each advisor saw a slice of the picture; no one saw the whole.
The fractional family office transition began with infrastructure:
- Establishing consolidated reporting across all entities.
- Creating a shared balance sheet view accessible to key advisors.
- Identifying where legacy structures were misaligned with current reality.
Once visibility improved, planning steps followed:
- Updating estate plans to reflect actual entity values and roles.
- Coordinating tax strategies across business and real estate.
- Modeling Freedom Point with distributions and cash flows from each structure.
This reduced the founder’s time in coordination, but more importantly, it improved decision quality. Refinancing, compensation changes, and investment moves were now made with whole system information.
Frequently Asked Questions
Do I Need To Replace My CPA Or Attorney?
In most cases, no. A fractional family office is a coordination model, not a replacement model. Existing CPAs and attorneys usually remain central members of the advisory team. The change is that they now work within a structured planning hub that manages cross domain information and keeps strategies aligned.
Replacement becomes relevant only when capacity, specialization, or fit is clearly insufficient for the level of complexity. Those decisions are made deliberately, with the founder, and with respect for long standing relationships.
How Does Cost Compare To What I Already Pay?
Fractional family office engagements are typically structured as planning retainers or annual fees tied to complexity, scope, and number of entities. The relevant comparison is not just current visible fees but also the hidden cost of fragmentation: tax inefficiencies, stalled decisions, exit value risk, and founder time spent as integrator.
For founders whose situation has outgrown lane based advice, the coordination value can support better outcomes and better use of existing advisor capacity. The fee is one input in a broader evaluation of risk reduction, clarity, and momentum.
How Is This Different From A Wealth Manager Or Financial Planner?
Wealth managers focus primarily on investments. Financial planners focus primarily on personal financial planning. Both can be valuable, but they are not designed to:
- Treat the operating business as the primary asset in the plan.
- Coordinate CPA and estate counsel around shared scenarios.
- Own the integrated planning system across business, personal wealth, tax, estate, and legacy.
A fractional family office owns the system. Wealth managers and planners operate as specialists within that system.
When Is The Right Time To Make This Transition?
Founders often act at obvious inflection points: a valuation milestone, a serious acquisition inquiry, a significant tax event, or a visible approach to exit. These moments sharpen urgency, but they also compress timelines.
The better trigger is recognition that current complexity exceeds what a fragmented structure can reliably handle. Running an Advisor Coordination Audit provides a practical test: if it reveals gaps you cannot close through current relationships and processes, it is time to consider a different model.
What Happens To Existing Advisor Relationships During Transition?
Transition is phased:
- Inventory and map the current ecosystem.
- Identify coordination gaps and outdated assumptions.
- Introduce the planning hub with clear scope and communication norms.
- Establish ongoing planning rhythms that keep the integrated plan current.
Existing advisors are invited into the system as partners. Many welcome the clarity, improved information flow, and more coherent client objectives.
How Long Does It Take To See Meaningful Change?
Founders typically see meaningful improvements in clarity and coordination within the first few months of structured work: better visibility, fewer conflicting recommendations, and more efficient use of meeting time. Full implementation of new planning rhythms and infrastructure may take several quarters, especially where entity structures are complex.
Is A Fractional Family Office Only Relevant If I Am Close To Exit?
No. Exit readiness is a central use case, but the coordination problem exists years before a sale. A fractional family office can be valuable in growth, stabilization, plateau, or second act phases. The model serves owners whenever business value, personal freedom, tax, and legacy decisions need to be made from one plan instead of several disconnected ones.
A Better Way To Move Forward
Founders who find themselves acting as the coordinator of their advisor team are carrying a role that should not sit on their shoulders indefinitely. The core shift is from “I will hold the pieces together by sheer effort” to “I want one system where business value, Freedom Point, tax, and legacy decisions are coordinated by design.”
A practical next step is to run an Advisor Coordination Audit against your current structure. Map your advisors, review work across the business value lifecycle, examine whether your business value shows up meaningfully in your personal wealth plan, and test alignment between exit and legacy goals. The findings will show whether coordination is a minor nuisance or a material risk.
If the gaps are material, the next move is a focused conversation about installing a planning hub. ClearPoint works with founders in the 5–75M range to design fractional family office models that respect existing relationships, coordinate technical work, and bring system level thinking to complex decisions. A clarity session is the place to explore whether a fractional approach fits your situation.
That conversation is designed to review your advisor landscape, planning cadence, and major decisions on the horizon. From there, you can decide whether to proceed with a compliance first, coordination focused assessment of how a fractional family office could support your business, personal wealth, and legacy goals, tailored to your existing stack and the journey you want your family to follow.